What's in your credit score?
What's in your credit score?
AT A GLANCE
- FICO® Scores are calculated using many different pieces of credit data in your credit report.
- This data is grouped into five categories: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%).
- Your credit report is the primary source of information used to calculate your credit score — personal details like income, age, and where you live don't factor in.
Your FICO® Score is made up of several key factors that lenders use to evaluate how you manage debt and financial responsibilities.
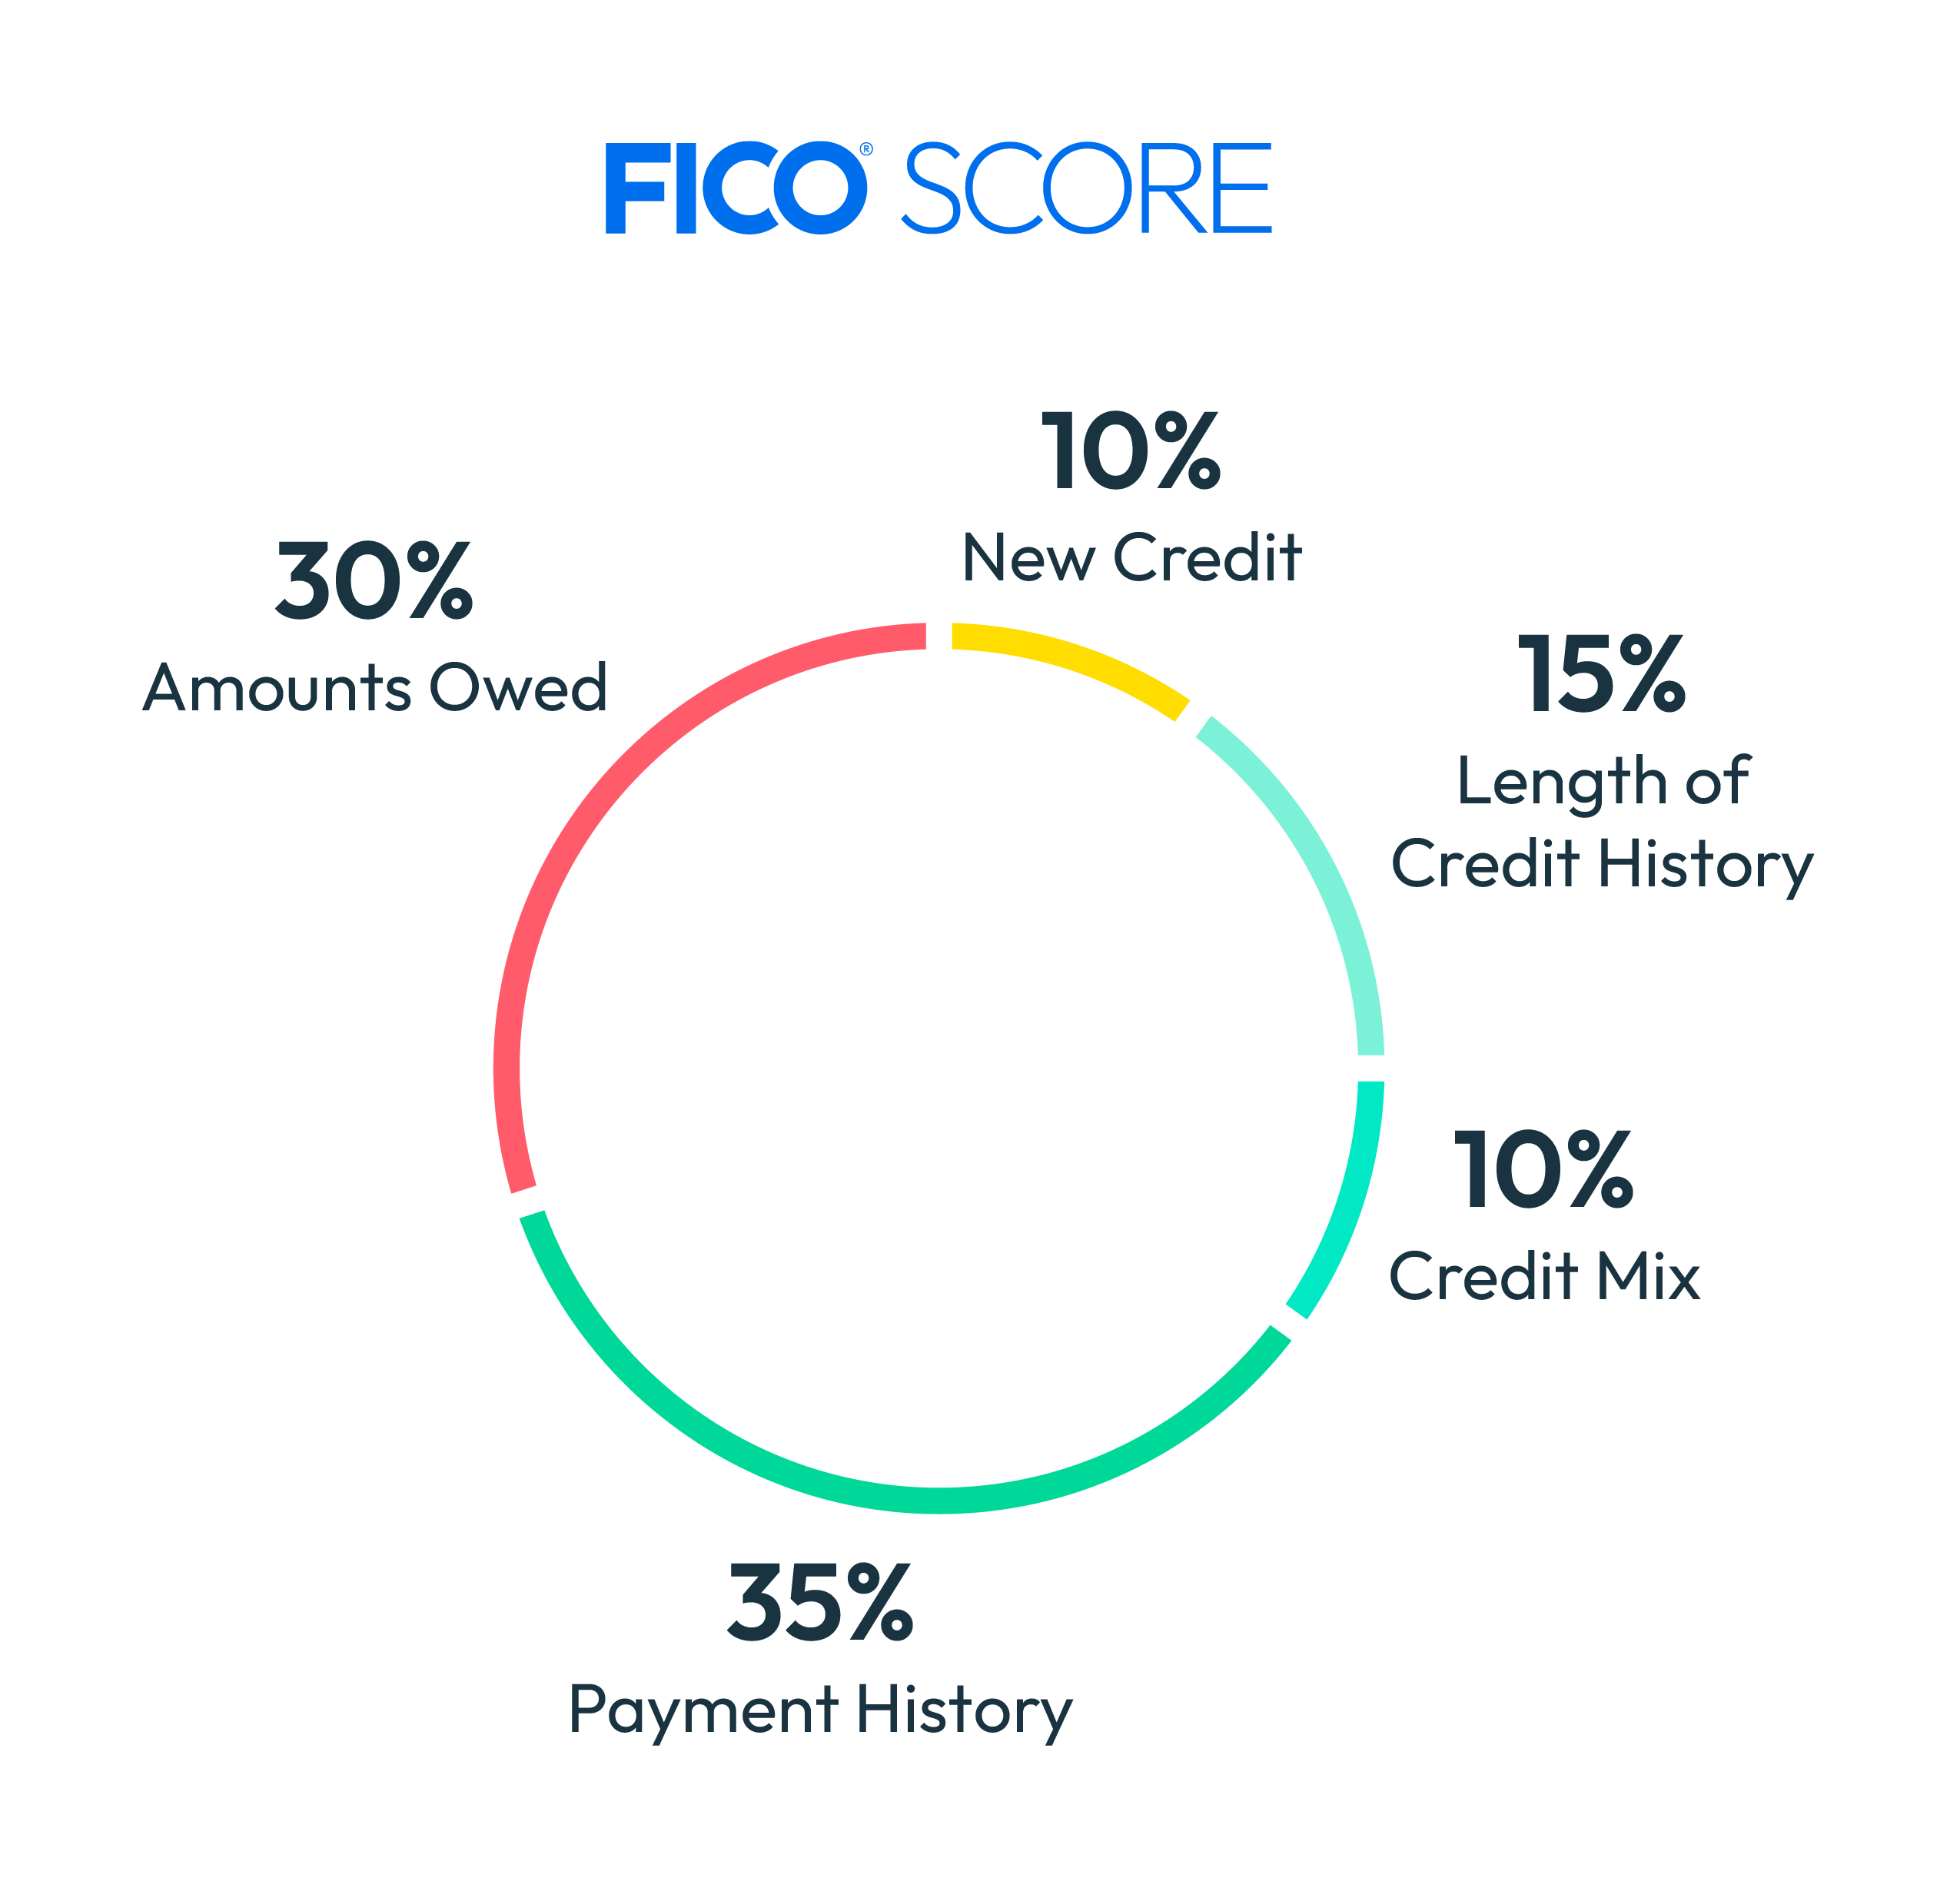
Your FICO® Scores consider both positive and negative information in your credit report. The percentages above reflect how important each of the categories is in determining how your FICO Scores are calculated. The importance of these categories may vary from one person to another.
FICO® Scores are based on your credit report
Your FICO® Score is calculated only from the information in your credit report (with the exception of your UltraFICO® Score, which considers consumer-permissioned banking account data). Credit report data includes positive information, like making on-time payments on a loan, and negative information, like missing a credit card payment.
However, lenders may look at many things when making a credit decision, such as your income, how long you have worked at your current job, and the kind of credit you are requesting.
Your FICO® Score does not factor in the following personal information:
- Your race, color, religion, national origin, sex, or marital status
- Your age
- Where you live
- Child or family support obligations
FICO® Scores also don't factor in the following financial information:
- Your salary, occupation, title, employer, date employed, or employment history
- Any interest rate being charged on a particular credit card or other account
- The type of credit you are requesting
However, lenders might assess some of these financial factors when making their own lending decisions.
Every FICO® Score calculation is unique
Your FICO® Scores are unique, just like you. Your credit report is a snapshot of your credit at a single moment in time. As the information in your credit report changes, so does the role each data point plays in determining your FICO Scores.
Because your report and scores are always evolving, it's not possible to measure the exact impact of a single factor on your FICO® Score without looking at your entire report.
What are the credit score factors?
Payment history (35%)
Payment history shows how you've paid your accounts over the length of your credit history. Research shows that your track record of payment tends to be the strongest predictor of the likelihood that you'll pay all debts as agreed, which is why it makes up 35% of your score.
The first thing any lender wants to know is whether you've paid past credit accounts on time. This helps a lender figure out the amount of risk it will take on when extending credit.
A few late payments are not an automatic "score-killer." An overall good credit history can outweigh one or two instances of late credit card payments. However, having no late payments in your credit report doesn't mean you'll get a "perfect score." Your payment history is just one piece of information used in calculating your FICO® Scores.
Learn more about payment history
Amounts owed (30%)
Amounts owed refers to how much debt you carry in total and how much of your available credit you are using. When a high percentage of a person's available credit has been used, this can indicate that a person is overextended and is more likely to make late or missed payments.
Not to worry if you have debt — it doesn't automatically make you a high-risk borrower. However, if you're using a lot of your available credit, lenders may assume that you're overextended and are at a higher risk of defaulting.
Length of credit history (15%)
In general, having a longer credit history is positive for your FICO® Scores, but it's not required for a good credit score. Even some people who haven't had credit for a considerable length of time can still have a high FICO Score if the rest of their credit report looks good.
Your FICO® Score takes into account:
- How long your credit accounts have been established, including the age of your oldest account, the age of your newest account, and an average age of all your accounts
- How long specific credit accounts have been established
- How long it has been since you've used certain accounts
Learn more about length of credit history
Credit mix (10%)
The types of credit you have are known as your credit mix. FICO® Scores will consider your mix of credit types, including:
- Credit cards
- Retail accounts
- Installment loans
- Finance company accounts
- Mortgage loans
It's not necessary to have one of each. Since credit mix is only 10% of your FICO® Score, it most likely won't be a key factor in determining whether or not you obtain credit from lenders.
New credit (10%)
New credit makes up 10% of a FICO® Score. Research shows that opening several new credit accounts in a short period of time represents greater risk — especially for people who don't have a long credit history.
When you apply for new credit, an inquiry is placed on your credit report. FICO® Scores only consider inquiries from the last 12 months, although inquiries remain on your credit report for two years.
Why does your FICO® Score matter?
Your credit score affects your loan and credit card eligibility, your rates, and the terms lenders may offer you. Understanding exactly what goes into your credit score can help you make informed financial decisions that support your goals.
FAQs about FICO® Scores
How do I choose the right credit monitoring plan?
To choose a credit monitoring plan that helps to explain your FICO® Score, look for services that scan your credit reports from all three bureaus, track changes over time, and offer educational resources that explain how each factor affects your score. A plan that provides your actual FICO Scores — not just a generic credit score — gives you the most accurate picture of what lenders see. Compare myFICO's credit monitoring plans.
What affects my credit score the most?
Payment history is the most influential factor in FICO® Scores, accounting for 35% of the calculation. Research shows that your track record of payment tends to be the strongest predictor of the likelihood that you'll pay all debts as agreed. A long history of on-time loan and credit card payments typically has a positive impact on your score, while missed or late payments can lower it.
How does credit utilization affect your credit score?
Credit utilization falls under "amounts owed," which accounts for about 30% of your FICO® Score calculation. Your credit utilization ratio on revolving accounts — the percentage of your available credit you're using — is an important factor. Using a high percentage of your available credit means you're close to maxing out your credit cards, which can have a negative impact on your FICO Scores. On the other hand, using a low percentage of your available credit can have a positive impact.
Where do I go if I need help with credit or finances?
If you need help with credit or finances, financial counseling can make a difference. Get advice on budgeting, credit report reviews, debt management, and more. Learn more about credit and financial counseling.